Introduction
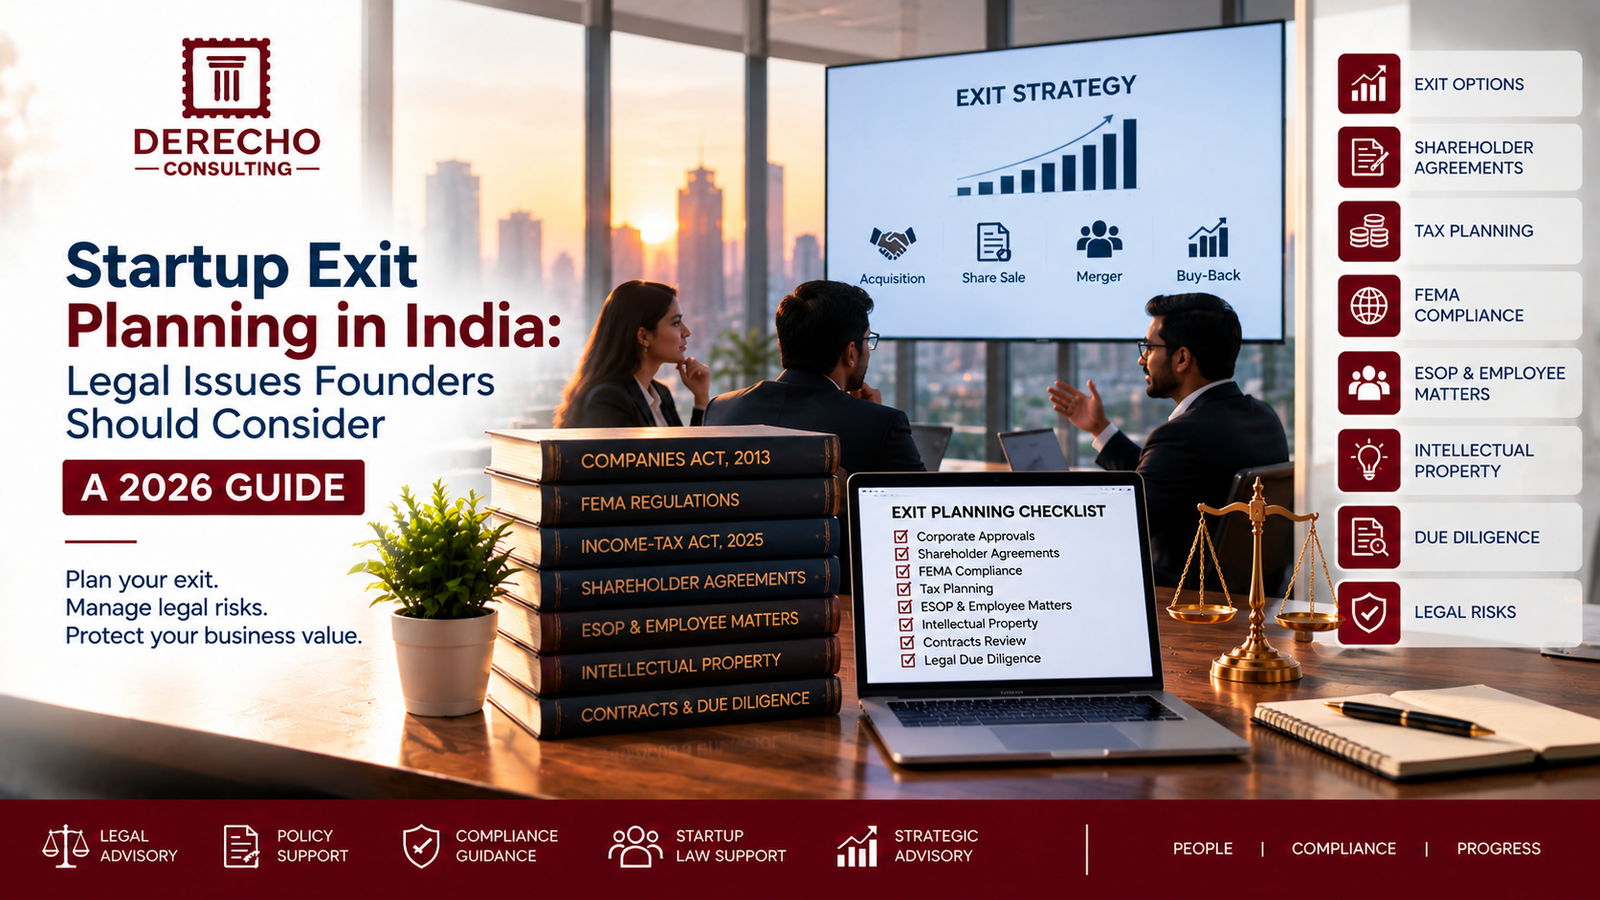
Startup Exit Planning is an important part of long-term business planning for founders, investors, and shareholders. A startup exit may involve a strategic acquisition, sale of shares, merger, buy-back, or another transaction that changes ownership or control. The legal process can involve corporate approvals, shareholder agreements, tax rules, regulatory filings, employee matters, intellectual property, and contractual obligations. Planning these areas early can help founders identify legal requirements before an exit transaction begins.
1. Choosing the Exit Structure
The legal requirements depend on how the exit is structured. A founder or shareholder may explore a direct share sale, acquisition of the company, merger or amalgamation, or a company buy-back where legally permitted. The Companies Act, 2013 contains provisions governing securities transfers and company buy-backs, while merger and arrangement transactions are subject to separate statutory procedures.
2. Review Shareholder Agreements
Before starting an exit, founders should review the shareholders’ agreement, articles of association, investment agreements, and other financing documents. Clauses relating to drag-along rights, tag-along rights, right of first refusal, reserved matters, transfer restrictions, investor consent, and exit rights can affect how a transaction is completed. Any contractual restriction should be identified before negotiations with a buyer begin.
3. Share Transfer and Corporate Records
A share sale requires proper documentation and corporate records. Section 56 of the Companies Act, 2013 governs transfer and transmission of securities, and the prescribed securities transfer form is SH-4 for applicable physical transfers.
Founders should also verify the cap table, share certificates or dematerialised holdings, past allotments, board and shareholder resolutions, and statutory registers. Gaps in ownership records can create delays during due diligence.
4. Foreign Investors and FEMA Compliance
Where a startup has foreign investors or a transaction involves a non-resident buyer or seller, FEMA and foreign-investment rules may apply. RBI regulations address the mode of payment, pricing, and reporting requirements for certain transfers of Indian equity instruments involving non-residents. Relevant transactions can require filings such as FC-TRS, depending on the transaction structure and parties involved.
5. Tax Planning for the Exit
Tax treatment should be reviewed before the transaction is signed. The nature of the transaction, holding period, type of securities, seller, consideration structure, and applicable exemptions or provisions can affect the tax position. The Income-tax Act, 2025 applies to tax years beginning on or after 1 April 2026, with transitional provisions for earlier periods.
6. Employee, ESOP and Benefit Obligations
A startup exit may affect employee contracts, ESOPs, incentives, retention arrangements, gratuity obligations, and employee benefits. Founders should review what happens to vested and unvested options, whether employee approvals are required, and whether employment-related liabilities will remain with the company or transfer under the proposed transaction.
7. Intellectual Property and Contracts
Intellectual property is often a major part of startup value. Before an exit, founders should confirm ownership of software, trademarks, copyrights, databases, inventions, domains, and other business assets. Customer contracts, vendor agreements, licenses, leases, loans, and technology agreements should also be checked for change-of-control, assignment, termination, or consent requirements.
8. Due Diligence and Legal Risks
A buyer will generally examine the startup’s corporate structure, financial records, contracts, employment matters, litigation, regulatory compliance, intellectual property, data practices, and investments. Missing filings, unresolved disputes, incomplete IP assignments, undisclosed liabilities, or inconsistent corporate records can become transaction issues. A structured legal due-diligence review can identify these matters before they affect negotiations.
9. 2026 Legal Considerations
For exits taking place in 2026, founders should account for the transition to the Income-tax Act, 2025, which applies from 1 April 2026, alongside the continuing Companies Act framework and applicable FEMA requirements. The exact compliance requirements will depend on the startup’s structure, investors, transaction type, and whether the transaction involves domestic or cross-border parties.
10. How Derecho Consulting Can Help
Startup Exit Planning should begin well before the final transaction documents are signed. Derecho Consulting can assist founders with corporate documentation, shareholder and investment agreement reviews, transaction structuring, due diligence, employment and ESOP matters, intellectual property checks, regulatory compliance, and exit documentation.
Conclusion
A startup exit is not only a commercial transaction; it can involve multiple legal, tax, corporate, employment, and regulatory considerations. Early Startup Exit Planning can help founders organise ownership records, review investor rights, identify contractual restrictions, prepare for due diligence, and address compliance requirements before closing the transaction.