1. Introduction
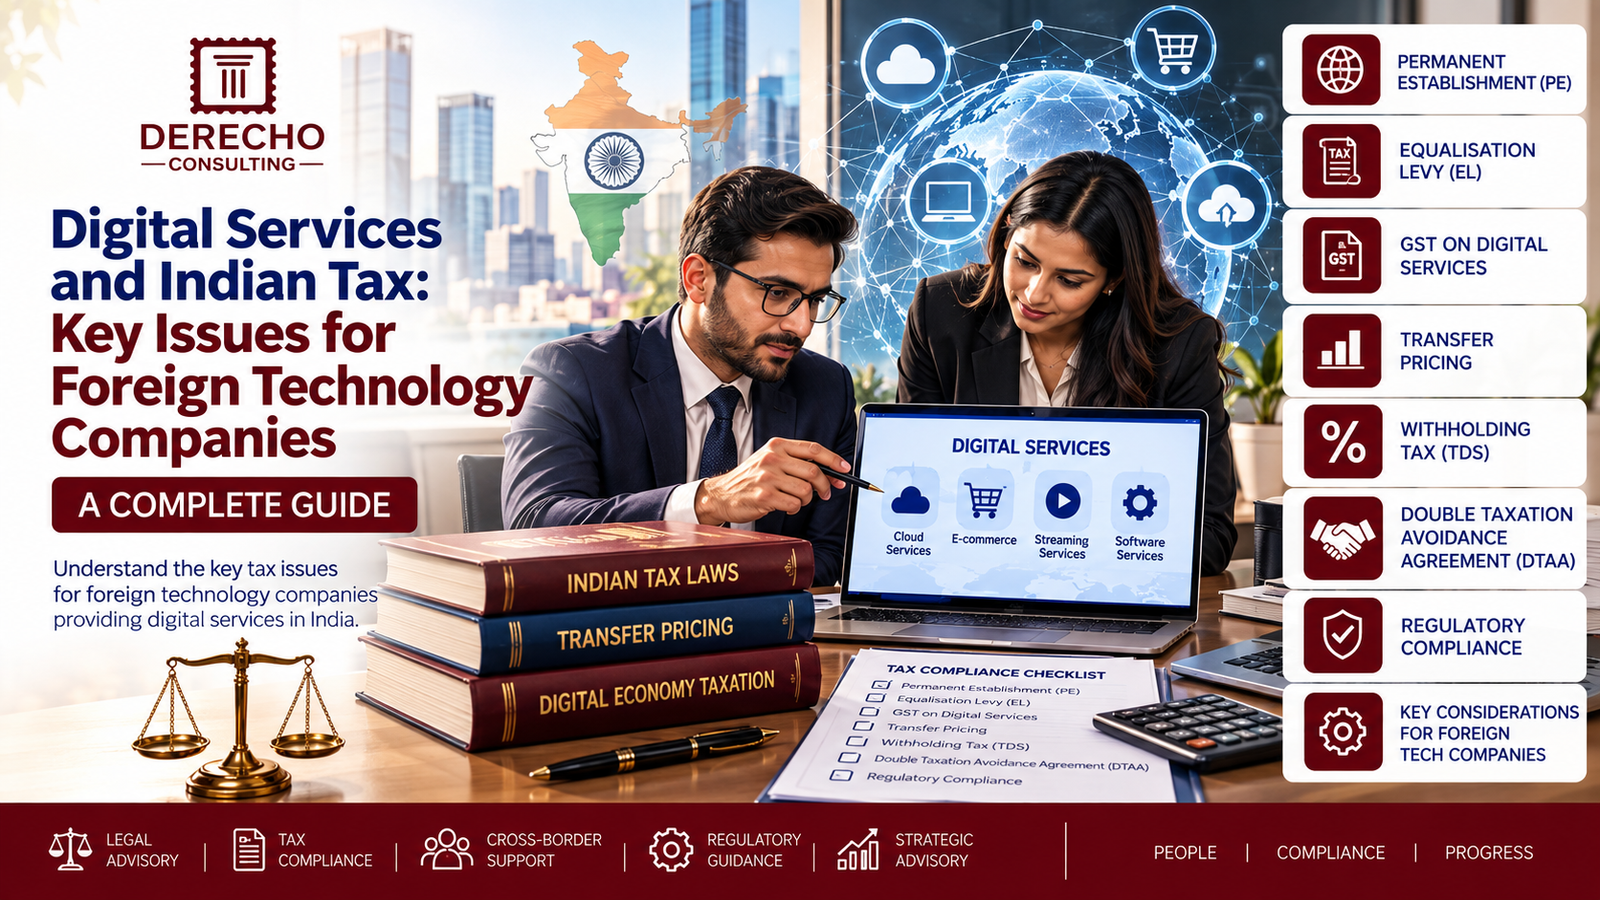
Digital Tax India is an important consideration for foreign technology companies serving customers in India. A company may provide software, cloud services, online platforms, digital advertising, data services, or technical services from outside India. The tax position can depend on the nature of the service, the Indian customer, the company’s business activities in India, and the applicable tax treaty. From 1 April 2026, the Income-tax Act, 2025 replaced the Income-tax Act, 1961, subject to transitional provisions.
2. When Can Indian Tax Apply?
A foreign company does not necessarily avoid Indian tax merely because it has no traditional office in India. Under the Income-tax Act, 2025, income from a business connection in India can be taxable in India. The Act specifically includes Significant Economic Presence (SEP) within the concept of business connection.
3. Significant Economic Presence
SEP is particularly relevant for digital businesses. The current rules prescribe a threshold of ₹2 crore for qualifying transactions with persons in India. They also prescribe a threshold of 3,00,000 users in India for the relevant digital interaction test. The Income-tax Act, 2025 also states that SEP can apply even when the agreement is entered into outside India or the foreign company has no residence or place of business in India.
4. Permanent Establishment and Business Presence
Foreign technology companies should also review whether their activities create a Permanent Establishment (PE) under an applicable tax treaty. Employees, dependent agents, fixed places of business, and contract-related activities can become relevant. The domestic law and the applicable Double Taxation Avoidance Agreement should therefore be reviewed together.
5. Software, Licensing, Royalty and Technical Services
Payments for software, technology licences, technical services, or consulting may require careful classification. The Income-tax Act, 2025 contains provisions dealing with royalty and fees for technical services (FTS). The treatment can vary based on the transaction and the applicable treaty.
6. TDS on Payments to Foreign Companies
Indian businesses making taxable payments to foreign companies should review their withholding obligations. Under the Income-tax Act, 2025, TDS provisions for non-resident payments are consolidated under Section 393. For payments made or credited from 1 April 2026, the new Act applies to the relevant withholding obligation.
7. GST on Digital Services
GST can create a separate compliance requirement. Online Information and Database Access or Retrieval (OIDAR) services include certain electronically supplied services such as online software, cloud services, digital content, and online advertising. A foreign supplier providing OIDAR services to a non-taxable online recipient in India can have GST registration and payment obligations under the applicable framework. For supplies to registered Indian businesses, reverse-charge rules may apply in specified cases.
8. Equalisation Levy: Check the Current Position
Foreign technology companies should avoid relying on outdated guidance about the Equalisation Levy. The 2% levy on e-commerce supply or services stopped applying to transactions on or after 1 August 2024. The 6% levy on specified online advertising services was also removed from 1 April 2025. Therefore, these former levies should not be treated as new 2026 charges.
9. 2026 Compliance Checklist
Foreign technology companies should review their Indian revenue, customer base, user numbers, contracts, service classification, PE position, SEP exposure, withholding requirements, GST position, and treaty benefits. They should also maintain supporting contracts and transaction records. The 2026 tax framework makes it important to keep digital-business tax documentation aligned with the Income-tax Act, 2025 and Income-tax Rules, 2026.
10. How Derecho Consulting Can Help
Digital Tax India issues often involve both direct and indirect taxes. Derecho Consulting can assist foreign technology companies with Indian tax exposure reviews, SEP and PE assessments, transaction classification, TDS analysis, GST and OIDAR compliance, treaty reviews, documentation, and ongoing regulatory monitoring.
Conclusion
The Indian tax position for foreign technology companies depends on how digital services are supplied and how the business interacts with the Indian market. Digital Tax India considerations can include SEP, PE, royalty and FTS classification, withholding tax, GST, and treaty provisions. Foreign businesses should review these areas before expanding their digital operations in India and should update their tax processes for the 2026 framework.